Portugal has published a decree extending exceptional storm-recovery waste measures through December 31. The change continues relief from the waste-management tax for qualifying Kristin debris while preserving the need to distinguish that material from ordinary waste.
Portugal’s storm debris recovery rules now have a further statutory extension. Decree-Law 202/2026, published on October 20, continues exceptional waste measures through December 31. It follows the Council of Ministers’ October 1 decision and responds to cleanup and reconstruction work that could not be completed by the previous September deadline.
A Recovery Deadline Has Outlasted the Emergency
The decree’s explanation says that procedures already underway, together with new municipal procedures for waste collection, removal, transport, treatment and onward management, would extend beyond September 30. The relevant activity is therefore a continuing recovery workload, rather than only the first clearance of roads and damaged properties after the storm.
The legal timing is explicit. The decree enters into force on the day after publication, while the amended provisions take effect from September 30. That combination addresses the interval between the earlier deadline and the later published extension. It gives the continued exceptional arrangements a stated legal time boundary instead of leaving the remaining work attached to an expired date.
The Relief Follows the Origin of the Waste
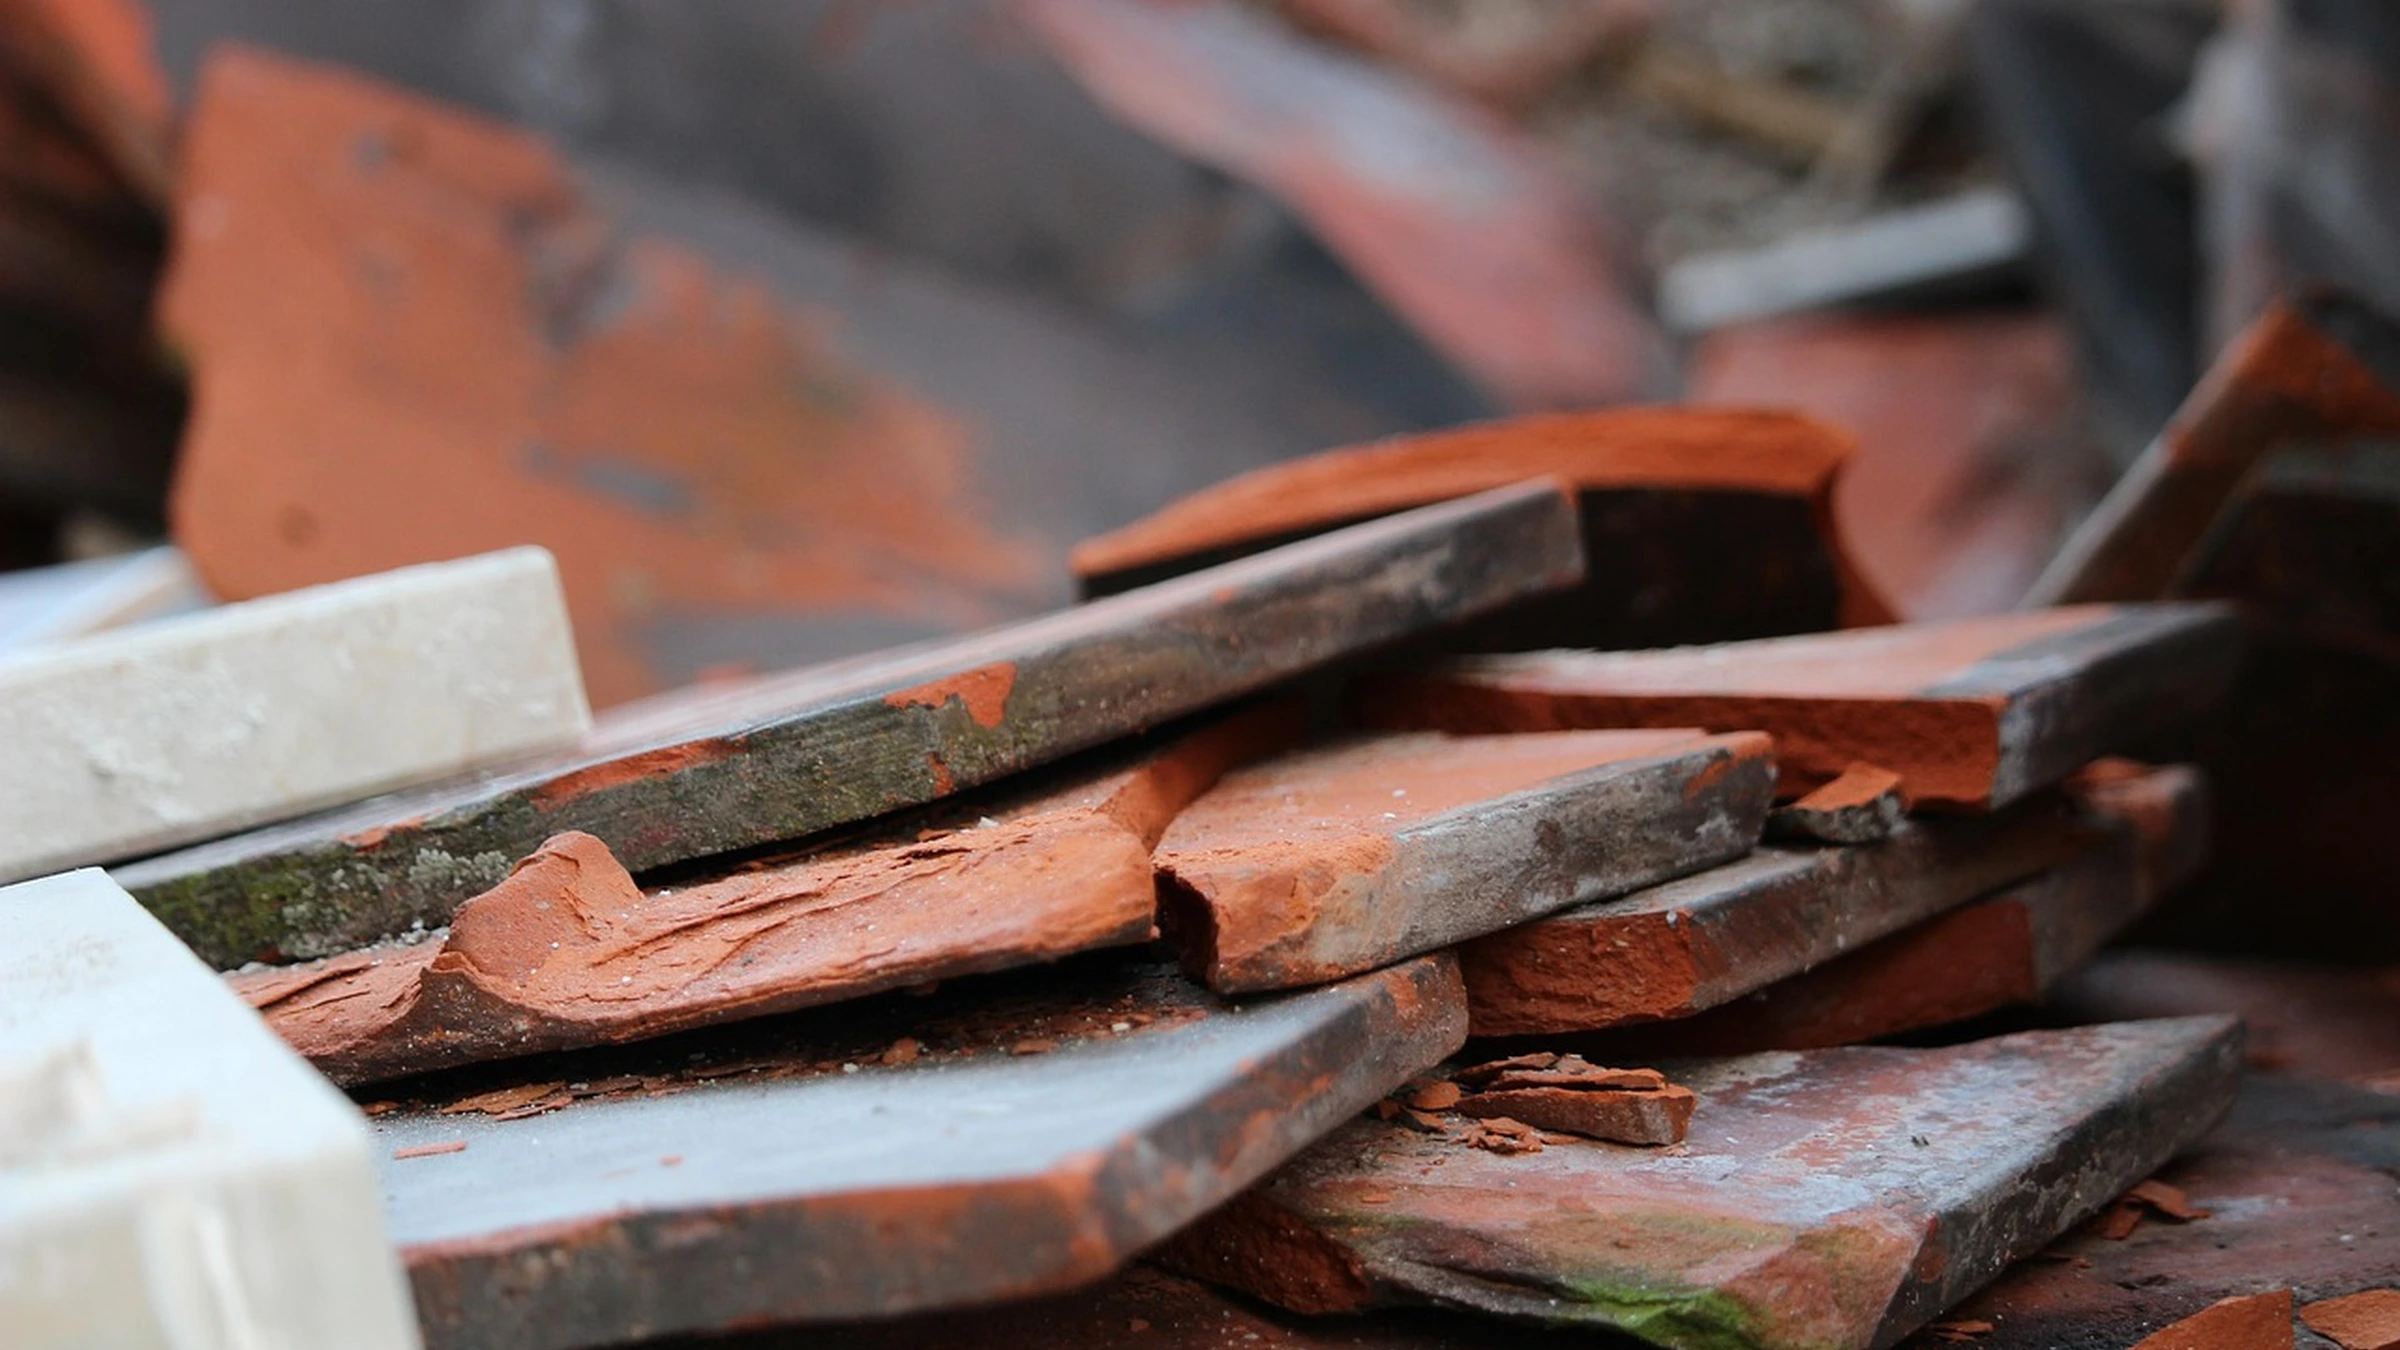
The original recovery regime identifies waste resulting from Kristin’s destruction and the subsequent cleanup, recovery and reconstruction work in affected municipalities. Its waste provisions include suspension of the waste-management tax. The government’s October announcement specifically links continued relief to debris that remains in affected territories, particularly construction and demolition material.
That origin test is central to the measure’s financial meaning. Waste produced through storm damage and recovery qualifies because of that connection. The extension should not be read as a general year-end exemption for unrelated municipal waste. The existence of an eligible recovery project does not, by itself, turn every other waste movement in the same territory into storm debris.
The original decree also provides for relevant quantities to be reported to the National Waste Authority for the 2026 tax settlement. This gives identification of the material an accounting consequence. Keeping a record of qualifying quantities supports the distinction between exceptional relief and the ordinary waste stream; an extension of time does not remove the need to establish which material the relief concerns.
Removing a Tax Does Not Remove the Work
The government presents the measure as a way to continue collection and treatment without adding the tax burden to municipalities and affected people. That is narrower than paying the whole cleanup bill. Transport, handling and treatment still require resources, and the October decree’s own explanation anticipates continuing municipal procedures to secure those activities.
For a municipality planning the remaining recovery work, the difference matters. An exemption can change the charge attached to a qualifying waste flow while leaving the task of arranging the service intact. It can ease one financial pressure without establishing that contractors have been appointed, that enough treatment capacity is available or that all debris has reached its appropriate destination.
The extension also preserves an end date. December 31 gives the continued measures a defined period, subject to any later extension provided by law. Municipal cleanup schedules and waste records need to reflect that boundary rather than treating emergency relief as a permanent change to the ordinary system.
The policy consequence is practical: recovery measures must remain usable for the duration of the recovery work they support. Portugal has aligned the exceptional waste provisions with a longer municipal workload. The next question is how much qualifying debris is collected and managed within that period, rather than whether the existence of tax relief alone establishes that recovery is complete.
Take-Out
Time-limited tax relief can support a longer cleanup, but its value depends on keeping the storm-related waste stream identifiable and connecting financial relief to actual collection and treatment.
Questions and answers
What readers should know
- What is the new end date?
- The relevant exceptional waste provisions now apply through December 31, 2026, subject to any further lawful extension.
- When was the new decree published?
- Decree-Law 202/2026 was published on October 20, with next-day entry into force and the stated effects from September 30.
- What waste does the relief concern?
- Qualifying waste from Kristin damage and the subsequent cleanup, recovery and reconstruction work in affected municipalities.
- Does the exemption cover all waste-management costs?
- No. Tax relief is distinct from the cost and organization of collection, transport and treatment.
- Why do quantities still matter?
- The original decree requires reporting of qualifying quantities for the 2026 tax settlement, so storm-related material must remain identifiable.
Stay in the loop
Keep Mark and Focus in view
Hear about future publications, announcements, and relevant updates from Mark and Focus.